Inflation in Chile accelerated unexpectedly in August
The central bank is taking a cautious and watchful stance on monetary policy. Inflation data for August in Chile came in higher than expected, quickly cooling market expectations for rate cuts.
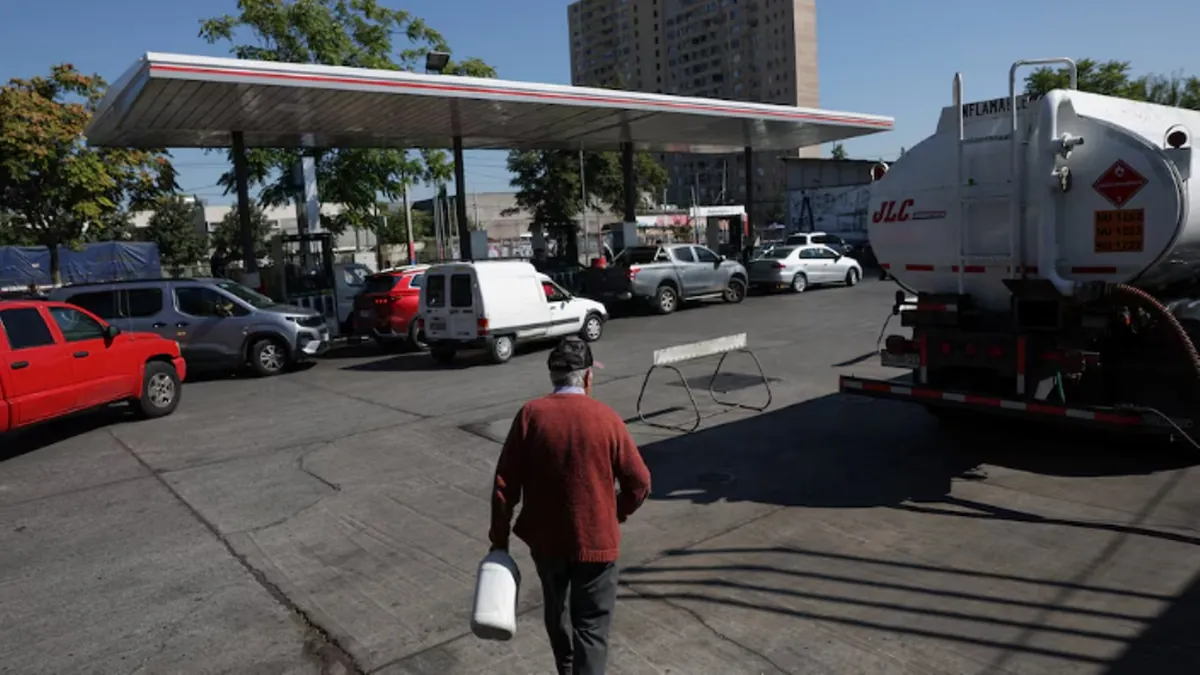
Inflation data shows a surprising rebound
Official statistics show that Chile's consumer price index rose by 0.6% year-on-year in August, a large increase from the 0.1% increase in July. This data not only reached the highest monthly growth rate since April this year but also largely outperformed market expectations. Chile's annual inflation rate rose from 3.5% in July to 4.1%, directly exceeding the central bank's reasonable fluctuation range of 3% ± 1%.
The inflation exceeding the standard again has brought direct pressure on local monetary policy. The market generally believed that Chile's inflation had entered a steady decline phase before and the central bank had the space to gradually cut interest rates and provide economic support. However, the unexpected inflation rebound in August directly reversed the market's expectation of easing.
The price increase is widespread
The monitoring data from the Chilean National Statistics Institute shows that among the 13 major categories of goods and services included in the domestic consumption price statistics, 9 categories saw a month-on-month price increase in August. The coverage of price hikes is extremely broad. Among them, the price of transportation services saw the most significant increase, rising by 1.6% month-on-month. Fluctuations in fuel prices and the increase in travel service costs are the main reasons for the price increase in the transportation sector.
The food and non-alcoholic beverage sector followed closely, with a month-on-month increase of 1.4% in August. Fluctuations in food prices are closely related to extreme weather. The El Nino climate phenomenon affected the local agricultural output, and the contraction of supply chains pushed up the cost of daily food consumption. Essential items such as clothing and transportation saw concentrated price increases. The prices of these essential goods are unlikely to quickly fall in the short term, which makes this round of inflation rebound have sustainability and is not a short-term temporary fluctuation.
The upward risk of inflation is accumulating
This round of inflation rebound in Chile is the result of the combined effect of internal climate factors and external market shocks. The difficulty of short-term inflation decline has increased. The El Nino weather disrupts the agricultural production rhythm, causing a shortage of local food supply and pushing up agricultural product prices. The supply shock brought by this weather will not quickly subside and will support food prices at a high level in the medium to long term.
At the same time, fluctuations in global energy prices continue to exert inflationary pressure. The international oil price fluctuates upward, driving up fuel and transportation costs in Chile, creating imported inflationary pressure, and further amplifying the local price increase. The inflation level predicted at the end of the year by the market was already low, and the central bank is likely to raise its inflation forecast for the year and revise the previous optimistic judgment.
The expectation of interest rate cuts has completely cooled down
The inflation exceeding the standard has changed the monetary policy rhythm of the Central Bank of Chile. Previously, the core of market speculation was when and by how much the central bank would initiate interest rate cuts. Now, the market is in a cautious wait-and-see stage. The latest inflation data is sufficient to support the central bank's cautious and tight policy stance. There is no space for any easing measures given the current price trend in Chile. Policy makers need to be restrained and focused on stabilizing inflation.
The market has formed a unified prediction. The Central Bank of Chile will maintain the benchmark interest rate at 4.5% at the monetary policy meeting of the current month. The expected start time of the interest rate cut cycle will be largely postponed. Taking the risk of cutting interest rates in the face of persistent inflation deviating from the target range will further stimulate demand and exacerbate price increases, contrary to the original intention of monetary policy regulation. Maintaining the interest rate unchanged is the current optimal choice.